Corporate Life Insurance Planning
Corporate Life Insurance Planning: Protect, Reward, and Plan for the Future
Running a business in often means wearing multiple hats—owner, leader, and long-term planner. But have you ever thought about what happens if you or a key person in your company passes away unexpectedly? Or how you might use your corporation to support retirement, reward top talent, or prepare for taxes when transitioning ownership?
Corporate life insurance is one of the most flexible and underused tools available to business owners. It helps protect your company, reduce taxes, and build lasting value—both during your working years and when it’s time to pass the business on.
Let’s look at how business owners are using corporate-owned life insurance to protect their companies and their families while preparing for the future.
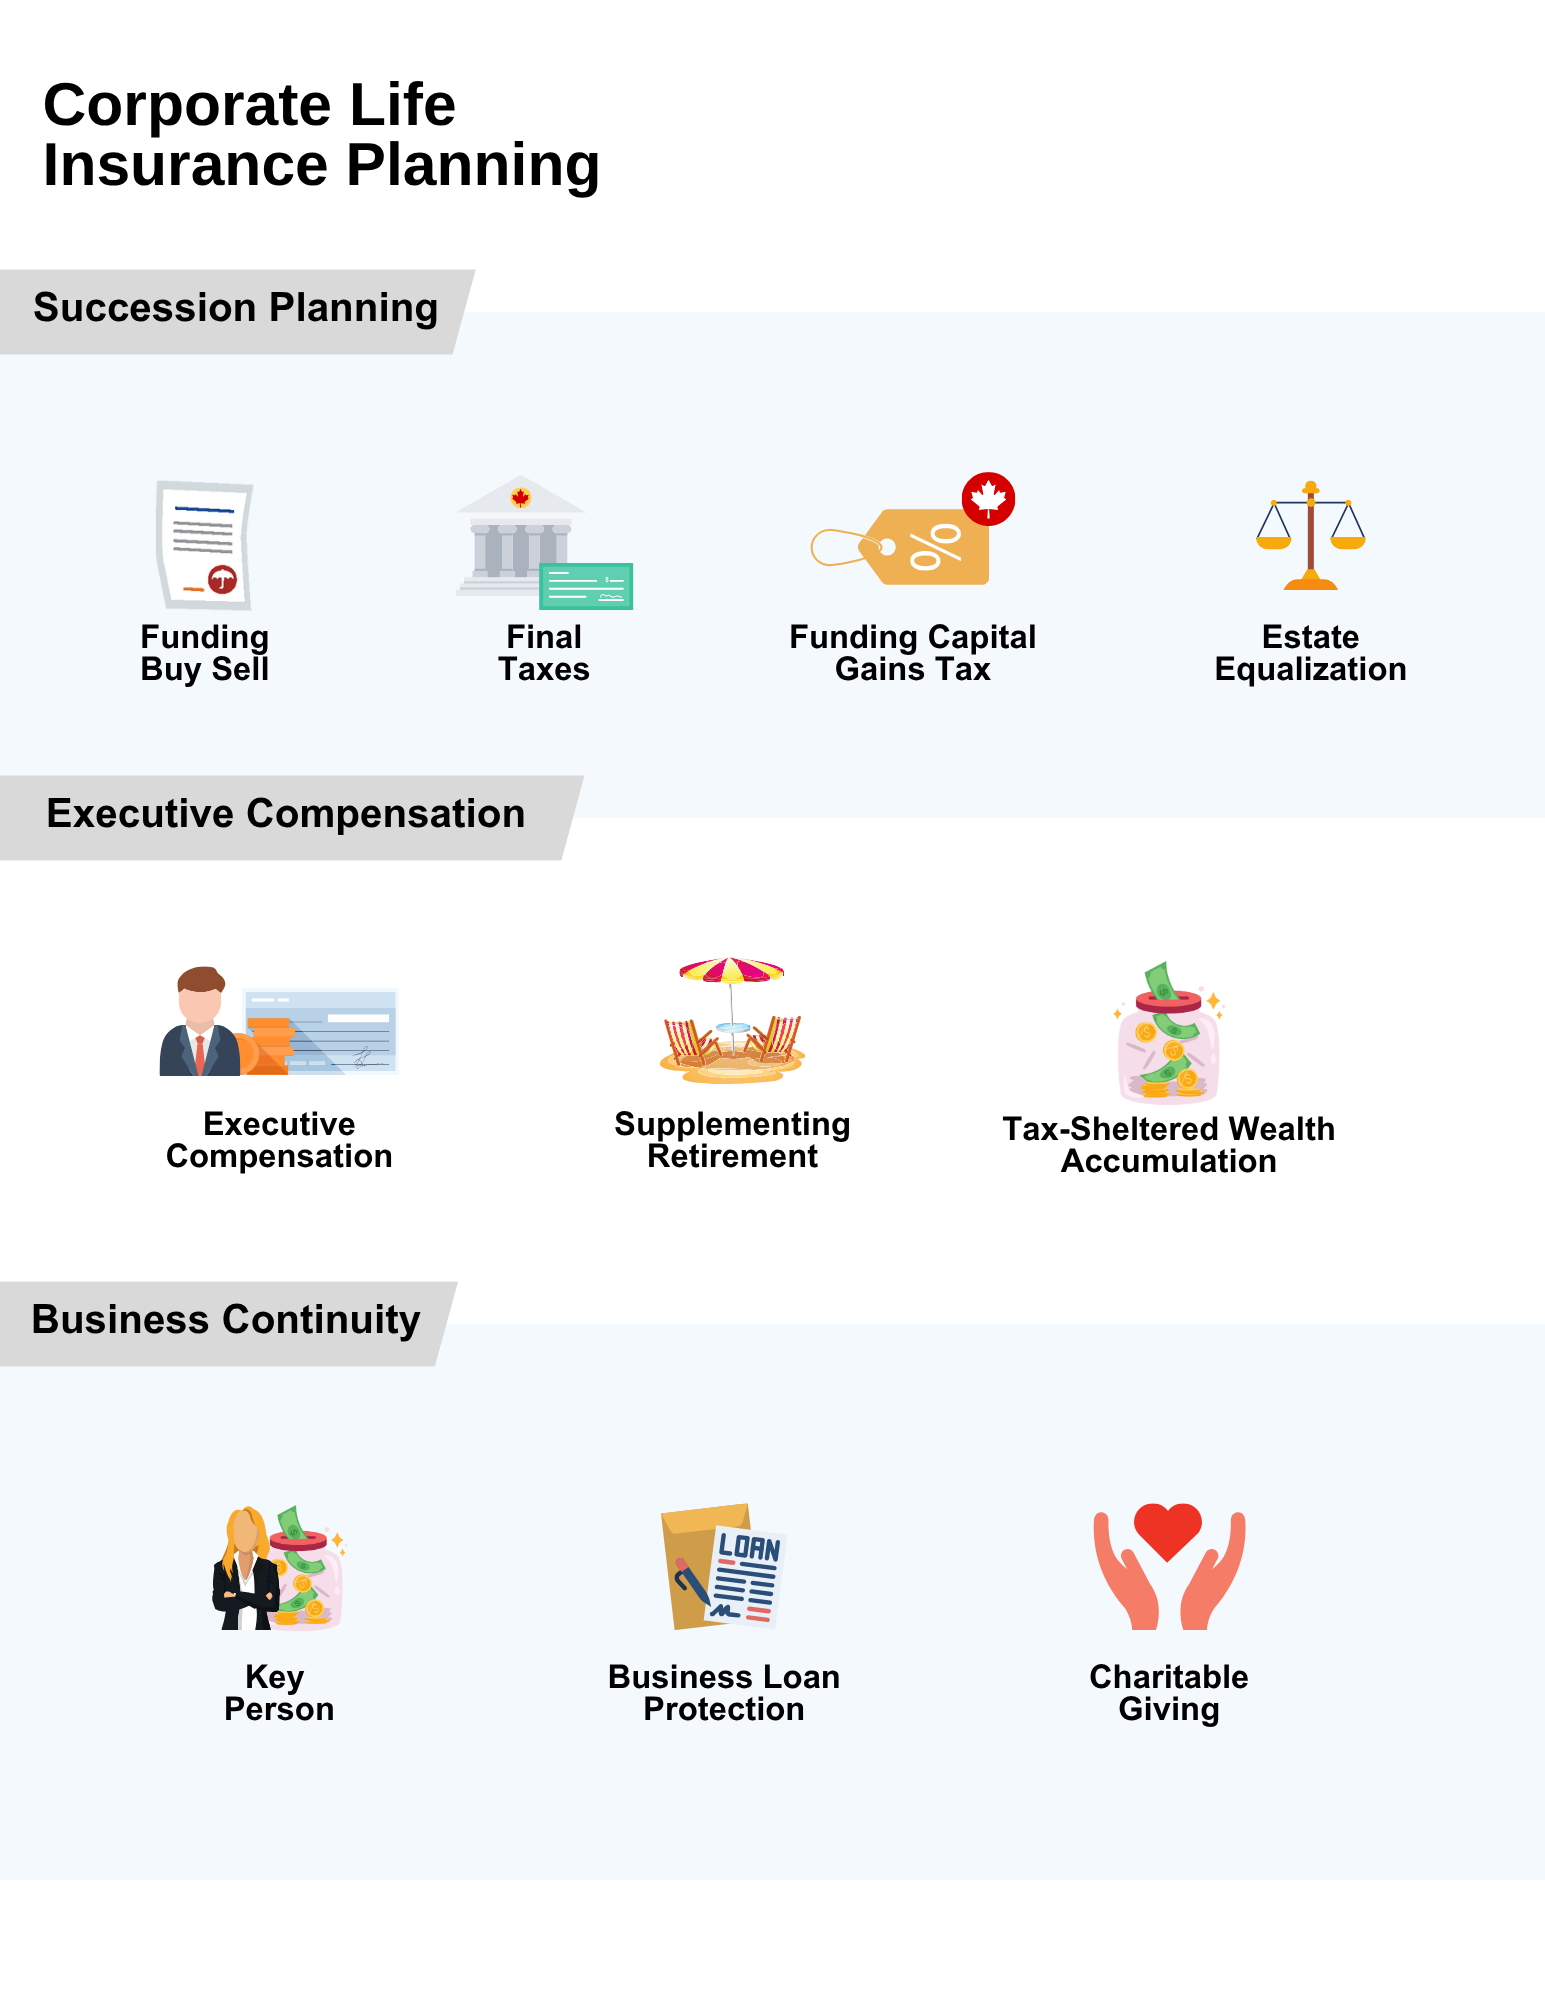
Succession Planning: Make Transitions Smooth and Tax-Smart
For many business owners, their company is one of their largest assets. But passing it on—whether to family or a partner—comes with major financial challenges. Life insurance can help.
Funding a Buy-Sell Agreement
If you have a business partner, a buy-sell agreement ensures that if one of you passes away, the other can buy the shares from the deceased’s estate. The problem? That buyout requires cash—often hundreds of thousands, if not millions. Life insurance is a cost-effective way to fund that agreement, so ownership stays in the right hands without putting a strain on the business or the family.
Covering Final Taxes and Capital Gains
When a business owner dies, the Canada Revenue Agency treats it as if they sold their shares—even if they didn’t. This “deemed disposition” creates a tax bill that can surprise even the most prepared families. Life insurance provides a tax-free lump sum that the corporation can use to cover this cost, helping preserve the value of the business and avoid selling off assets under pressure.
Estate Equalization
If you plan to leave the business to one child but want to treat your other children fairly, life insurance can help. The business goes to the child who’s involved, while other beneficiaries receive the life insurance proceeds. It’s a clean, tax-efficient way to avoid family conflict and keep the business whole.
Executive Compensation: Attract and Retain Top Talent
In a competitive hiring environment, offering the right benefits can make all the difference. Life insurance isn’t just about protection—it can be a powerful way to reward and retain your most valuable people.
Executive Compensation Strategies
Life insurance can be part of a compensation package that rewards top performers, especially those who are key to the company’s success. Whether structured as a bonus plan or part of a long-term incentive, this can be a powerful way to align goals and build loyalty.
Supplementing Retirement
Permanent life insurance policies—such as whole life or universal life—can accumulate cash value over time. This cash value grows tax-deferred and can later be accessed through policy loans or collateralized lending. For business owners and executives, this provides an additional, flexible income source in retirement, especially when RRSP and TFSA contribution limits have already been reached. It allows the corporation to efficiently use surplus cash while providing long-term financial flexibility and security.
Tax-Sheltered Wealth Accumulation
The cash value inside a permanent life insurance policy grows on a tax-deferred basis. When a corporation owns the policy, this growth can be especially strategic. It allows the business to use surplus cash to build value in a tax-efficient way, diversify beyond traditional investments, and potentially access funds later with fewer tax consequences. This approach is particularly useful for businesses with retained earnings that would otherwise be subject to higher corporate tax rates.
Business Continuity: Protect What You’ve Built
An unexpected death can do more than cause emotional pain—it can disrupt operations, shake client confidence, and even put the business at risk. Insurance helps ensure your company can keep going.
Key Person Protection
If you or someone else is essential to the day-to-day success of your business, losing that person could be a major financial blow. A life insurance policy on that individual can help the business recover, cover short-term losses, and fund the search for a replacement.
Business Loan Protection
Many lenders require insurance on owners or key executives as a condition of financing. If that person passes away, life insurance ensures the loan is paid off, protecting both the lender and the company’s assets. It can also unlock better lending terms and help avoid personal guarantees.
Charitable Giving Through the Corporation
For business owners looking to give back, corporate life insurance can also be used to support charitable causes. The business can own a policy and name a charity as the beneficiary—creating a lasting impact while offering potential tax benefits.
Bringing It All Together
Corporate life insurance isn’t just about “what if”—it’s about building a stronger, more resilient business and unlocking smart ways to manage wealth inside your company. Whether you’re focused on succession, rewarding your team, or protecting operations, insurance can help you take action today that pays off for years to come.
If you haven’t reviewed your corporate insurance strategy recently, now’s a great time to take a fresh look.
Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or tax advice. Always consult a qualified professional regarding your specific situation. We are not responsible for any actions taken based on this content.